Licensed health insurance advisors
Health coverage, made clear.
We compare Marketplace (ACA) plans and private PPO options side by side, and explain the trade-offs in plain language.
- Even if you missed open enrollment
- Even if you just lost employer coverage
- $0
- Advisor fee
- 1-on-1
- Personal guidance
- Year-round
- Private enrollment
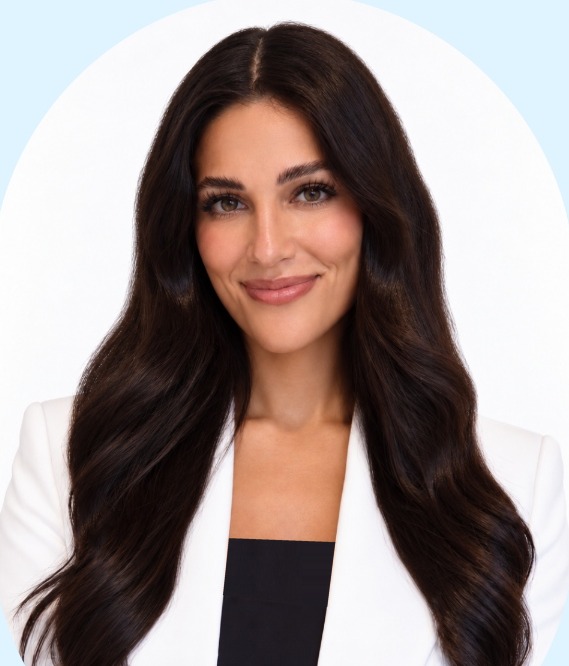
Meet the founder
Professional guidance. Personal accountability.
I spent six years in the insurance industry before a major medical setback of my own showed me what it's like to sit on the other side of the table.
That experience is why I started Pristine Health Advisors. Every client deserves a straight answer, a plan they understand before they need it, and someone who picks up the phone when it matters.
Alexa Smith
Founder & Senior Health Advisor
Meet your advisors
Look up any licensed advisor by name or National Producer Number (NPN) on the Florida DFS Licensee Search
Who we help
Different lives. Different coverage needs.
If one of these sounds like you, a short conversation is the best place to start.
Individuals & families
First plan, growing family or a premium that keeps rising. We weigh cost against the care you actually use.
Self-employed & 1099
Freelancers, contractors and owners who need portable coverage that isn't tied to an employer.
Small businesses
Start with team size, budget and priorities. We outline the coverage arrangements available to you.
Families on an employer plan
Adding a spouse or children can be expensive. Employer-split coverage keeps you on your work plan and places family on their own.
Early retirees
Retiring before 65 and need solid coverage until Medicare. We find a plan that bridges the gap.
Not sure where you fit?
Tell us a little about your situation and we'll take it from there.
Talk to an advisorCoverage options
Two kinds of plans outside of employer coverage. We know both.
Marketplace and private plans work differently. We compare both for your household and show you where each one makes sense.
Marketplace
ACA plans
Government-regulated major medical coverage available through the Health Insurance Marketplace.
- Priced by income, age and ZIP code
- Tax credits may lower premiums for eligible households
- Pre-existing conditions are covered; no health questions
- Enrollment during open enrollment or after a qualifying life event
Often a strong fit for households that qualify for savings, and anyone managing ongoing health needs.
Private
PPO plans
Health-based plans from established carriers, with nationwide provider networks.
- Priced by health, age and ZIP code
- Apply any time of year, no enrollment window
- Nationwide PPO networks with no referrals required
- Short health application; some conditions may be limited or excluded
Often a strong fit for healthy individuals, families and self-employed people who earn above subsidy levels.
Plan types
PPO, HMO or EPO? Here's the difference.
The letters on your plan decide which doctors you can see and how. Here's how the three most common types compare.
| PPO | HMO | EPO | |
|---|---|---|---|
| See a specialist without a referral | Yes | No | Yes |
| Out-of-network coverage | Yes | Emergencies only | Emergencies only |
| Primary care doctor required | No | Yes | Usually no |
| Network size | Largest, often nationwide | Local or regional | Local to regional |
| Typical premium | Higher | Lowest | Middle |
Not sure which one you have now? Send us your current plan and we'll tell you exactly what it covers.
Common situations
Something changed? Here's your window.
Timing matters in health insurance. These are the situations we help with most.
Lost employer coverage
Leaving a job opens a Special Enrollment Period. We compare COBRA, Marketplace and private options before it closes.
Missed open enrollment
Private PPO plans accept applications any time of year, so you don't have to wait until November.
Turning 26
Aging off a parent's plan qualifies you to enroll. We'll line up coverage that starts the day the old plan ends.
Premium increase
If your renewal went up, we'll compare what you have against current options before you pay another month.
Marriage or a new baby
Adding someone to your household is a qualifying life event. We'll help you decide whether to add them or cover them separately.
Moving states
Networks and prices change by state. We'll find a plan that works where you're headed.
How it works
Three steps. No guesswork.
-
Step one
We listen
Your doctors, prescriptions, budget, household and any current coverage. That's all we need to start.
-
Step two
We compare
Networks, deductibles and out-of-pocket costs, side by side.
-
Step three
You enroll
We handle the application and remain your point of contact after you're covered.
What we review before you decide
- Doctors & provider networks
- Prescription coverage
- Premiums & out-of-pocket costs
- Benefits, limitations & exclusions
- Eligibility & enrollment timing
Coverage we offer
Everything around your health plan, too.
Most clients start with medical coverage. We can build out the rest of your protection in the same conversation.
Medical / major medical
ACA and PPO plans for individuals, families and the self-employed.
Dental & vision
Standalone or bundled with your plan.
Life insurance
Term and permanent options.
Critical illness & accident
Cash benefits when the unexpected hits.
Income protection
Short-term disability coverage.
Small business coverage
Group options for owners and teams.
Ask about your team →Client reviews
Real people. Real coverage.
[Client review #1 goes here]
[Client review #2 goes here]
[Client review #3 goes here]
Refer a friend
Know someone overpaying?
Send them our way. We'll take good care of them.
Questions, answered
Straight answers before we talk.
Don't see your question? Ask an advisor and we'll walk you through it.
What if I don't qualify for a private plan?
You still have options. We'll walk you through the Marketplace plans available to you and help you enroll.
Can I keep my current doctors?
In many cases, yes. We check your doctors and hospitals against each plan's network before you apply, so you know where you stand.
I already have insurance. Can you still help?
Yes. We'll review what you have now at no cost. If a better option exists, keep your current coverage in place until the new plan is approved.
My employer offers coverage. Should I still talk to you?
Often, yes. Adding a spouse or children to a work plan is frequently expensive. Employer-split coverage keeps you on your work plan and places your family on their own.
Can I sign up outside open enrollment?
Yes. Private PPO plans accept applications year-round. Marketplace plans require open enrollment or a qualifying life event, like losing coverage, moving or having a baby.
Am I locked into a year-long contract?
No. You can cancel a private plan at any time. Marketplace plans run for the calendar year, but you can change plans after a qualifying life event.
Do pre-existing conditions affect my options?
Marketplace plans cover pre-existing conditions with no health questions. Private plans ask a short set of health questions, and some conditions may be limited or excluded. We'll tell you up front which route makes more sense.
Is there a fee for your help?
No, our help is always free to you. Our advisors are paid a base hourly rate rather than commission, so there's never any pressure toward one plan over another. We just want you in the plan that fits you best.
One conversation. Every option on the table.
We'll help you find coverage that fits your life and budget.